
Peer-to-peer crypto trading remains a common route for Indians converting rupees into stablecoins such as USDT, but it carries banking risk: money received from a counterparty may later be linked to cyber fraud.
How P2P Trades Trigger Freezes
The risk is concentrated on the receiving side. The chain often begins when a fraud victim reports stolen money through the National Cybercrime Reporting Portal. Investigators follow the transaction trail. If disputed funds subsequently reach a P2P seller, that recipient’s account can become part of the investigation.
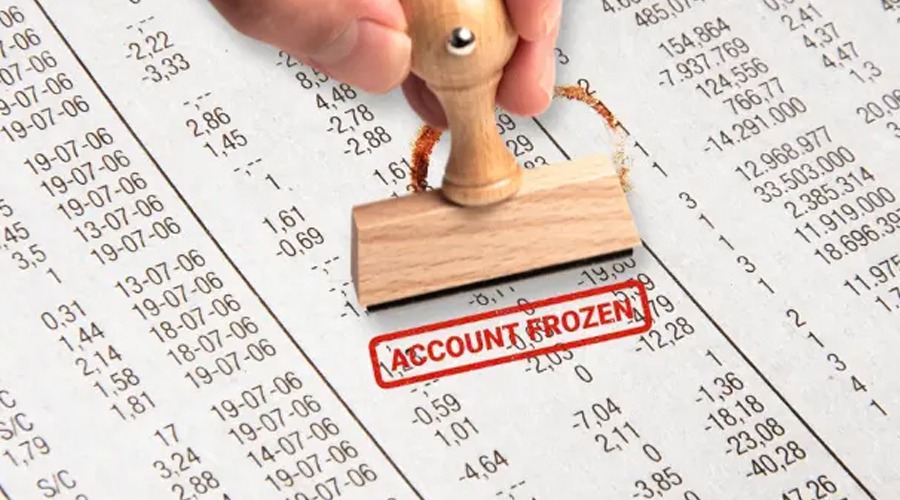
A lien generally restricts a specified amount, whereas a debit freeze can prevent use of the entire account, potentially disrupting access to salaries, UPI payments, savings and scheduled monthly EMIs.
BNSS Changed the Legal Framework
The Bharatiya Nagarik Suraksha Sanhita replaced the CrPC on July 1, 2024. Section 106 concerns seizure of property during investigation, while Section 107 provides a process for attaching suspected proceeds of crime.
In Headstar Global Pvt. Ltd. v. State of Kerala, the Kerala High Court held that attachment of a bank account under Section 107 requires an order from the jurisdictional magistrate.
The Kerala ruling distinguished attachment from evidence-preserving seizure. The Delhi High Court reinforced this approach in Malabar Gold and Diamond Ltd. v. Union of India in January 2026. According to the court, blanket freezing of accounts belonging to people who are neither accused nor suspects is ‘arbitrary’ and ‘disproportionate.’
Lowering P2P Banking Risk
Risk reduction therefore depends on documentation and limiting exposure. Keeping P2P activity separate from salary accounts, screening counterparties and preserving order IDs, chats, UPI references and exchange records can provide evidence if transactions are questioned.
If an account is frozen, users should obtain the complaint number, disputed amount and investigating jurisdiction from their bank. They can contact the investigating officer, submit transaction records and seek legal advice where a blanket freeze lacks the required judicial process.
Final Thoughts
P2P trading creates counterparty risk beyond crypto-price volatility. Strong records and careful banking practices cannot eliminate exposure, but they can make legitimate transactions easier to demonstrate when disputed funds enter the banking trail.
Also Read: India Crypto Rules: Why Clearer Licensing Could Change the Market
Disclaimer : Crypto News India does not recommend that any cryptocurrency should be bought, sold, or held by you. Do conduct your own due diligence and consult your financial advisor before making any investment decisions.
